Liked this video? Watch more in our full video series →
Dawn — Senior Seller Finance Note Advisor & Analyst
Moxxie Asset Group · Ft. Lauderdale, FL
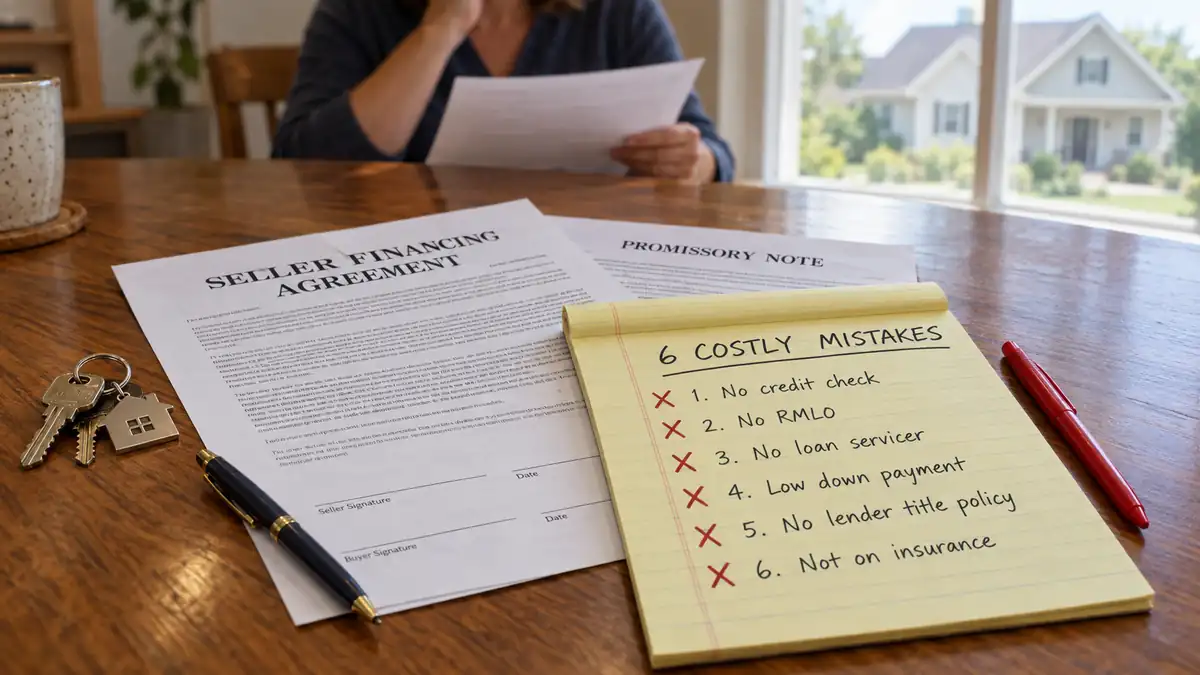
The Six Mistakes at a Glance
- →Pull your borrower’s credit — the single most common mistake, and the easiest to fix
- →Use an RMLO — real credit and income analysis, paid by your borrower at closing
- →Use a third-party servicer — clean records, compliance, and a paper trail if a dispute arises
- →Get a real down payment — 15 to 20 percent or higher signals commitment and builds your cushion
- →Get a lender’s title policy — not just an owner’s policy; they protect different parties
- →Be named on the homeowner’s insurance — as the lender, so you are notified and protected
If you’re thinking about selling your property and financing the sale yourself, then using seller financing can be a smart way to open your buyer pool, earn interest income, and close faster than a traditional bank-financed sale. But when you agree to seller finance, you’re not just selling a property anymore, you’re stepping into the role of the bank. And most sellers have never done that before. If you’ve ever asked yourself, “Should I sell my mortgage note?”, this information will help you think it through. We buy mortgage notes nationwide, and understanding these details can help you sell mortgage note payments on the best possible terms.
Prefer to watch instead? Watch the full video walkthrough — Dawn covers all six mistakes in under five minutes.
Our team has reviewed thousands of seller-financed notes over the years, and the same avoidable mistakes come up again and again. Here’s what to watch for, and how to structure your note the right way from the start.
Mistake #1: Not Pulling Your Borrower’s Credit
This is the single most common mistake we see, and it’s usually not because sellers don’t care. It’s because they simply don’t know how, or don’t know there’s an easy way to do it. Unlike a bank, most individual sellers don’t have direct access to the credit bureaus.
But here’s the thing: being a good person and being able to reliably make a payment every month for the next 15 or 20 years are two different things. Skipping this step means you’re extending significant credit based on trust alone, with no real data behind it. The next pitfall is actually a great tip on HOW to get that borrower’s credit pulled — at NO COST to you as the note creator. If you're considering selling a mortgage note, a free review is the simplest way to see where you stand.
▶ Watch: Dawn explains exactly why this step matters, and how an RMLO handles it for you, in Why It Is Important to Pull Your Borrower’s Credit Before Selling Your Property Using Seller Finance, or read the in-depth article: Why Pulling Your Borrower’s Credit Matters Before You Seller Finance.
Mistake #2: Not Using an RMLO
An RMLO, or residential mortgage loan originator, solves the credit problem above and does more. During closing, your borrower can pay for this service as a closing expense (so this is an enormous value to you and the health of your note and also ZERO cost to you). The RMLO pulls their actual credit report and runs a real financial analysis: income, existing debts, and whether they can genuinely afford the payment you’re about to agree to. That gives you real numbers to make your decision on, not a gut feeling because this is a good person.
Mistake #3: Skipping a Third-Party Note Servicer
Once your note is in place, someone has to collect payments, track taxes and insurance, keep you compliant with state laws and keep clean, professional records. Without a third-party servicer handling that, it falls on you, manually, for years. And if a dispute ever comes up, whether it’s a missed payment or a disagreement over terms, you won’t have a clean paper trail to fall back on. A servicer isn’t just convenience, it’s protection. You can also have your borrower pay for the monthly service fees as part of their monthly mortgage note costs.
Free — No Obligation
Already Holding a Note You Created?
Our team will review how your note is structured and what it’s worth in today’s market — no fees, no pressure, no obligation.
Mistake #4: Accepting Too Small a Down Payment
Your borrower’s down payment is one of the strongest signals of how seriously they’ll treat this obligation. A down payment in the 15 to 20 percent range, or higher, shows real financial commitment from your borrower (less likely to walk away from the property and the mortgage obligation when times get tough) and gives you a genuine equity cushion if something goes wrong down the road. A small or nonexistent down payment leaves you far more exposed. Selling a note is often simpler than note holders expect.
Mistake #5: Getting the Wrong Title Policy
This one catches a lot of sellers off guard, because many don’t even know it exists. When you seller finance, you need a lender’s title policy, not just an owner’s title policy. They protect different parties. A lender’s title policy protects you specifically in your new role as the lender, the same way a bank would be protected on a traditional mortgage.
Mistake #6: Not Being Listed on the Homeowner’s Insurance Policy
Make sure you’re named on the property’s homeowner’s insurance policy as the lender. If there’s ever a fire, storm, or other damage to the property, you want to be notified and protected too, not left to find out after the fact.
What Makes a Note Hold Its Value
Beyond avoiding these six mistakes, how you structure your note also affects what it’s worth if you ever decide to sell it down the road. A few things that consistently hold up best:
- Owner-occupied, single-family homes tend to hold their value better than other property types like investment properties, land or condos.
- Fully amortized loans, where the balance steadily pays down over time, are worth more than interest-only loans, where the balance never decreases.
We’re Not Just Note Buyers, We’re Seller Financing Advisors
At Moxxie Asset Group, our goal is to help note creators, note holders, and note sellers make informed decisions at every step of the seller financing process, whether you’re just getting started or you’ve been holding a note for years. Watch our full video walkthrough of these six mistakes, or reach out anytime for a free, no-obligation note review. You never have to sell a note before you're ready.
📞 954-466-7111
🌐 www.MoxxieAssetGroup.com
Frequently Asked Questions
Do I really need to pull my borrower’s credit if I am seller financing?
Yes. Being a good person and being able to reliably make a payment every month for the next 15 or 20 years are two different things. Skipping this step means you are extending significant credit based on trust alone, with no real data behind it. Most individual sellers do not have direct access to the credit bureaus, which is why this is the most common mistake we see — but an RMLO solves it, and your borrower can pay for that service as a closing expense, at no cost to you.
What is an RMLO, and who pays for it?
An RMLO is a residential mortgage loan originator. The RMLO pulls your borrower’s actual credit report and runs a real financial analysis: income, existing debts, and whether they can genuinely afford the payment you are about to agree to. That gives you real numbers to make your decision on, rather than a gut feeling. During closing, your borrower can pay for this service as a closing expense — an enormous value to you and to the health of your note, at zero cost to you.
I already created my note — is it too late to fix any of this?
No. Several of these are fixable after closing: you can move collections to a third-party servicer, ask to be named on the homeowner’s insurance policy as the lender, and confirm which title policy was actually issued. If you would like to know what your note is worth today, gather your mortgage or deed of trust (depending on your state), your promissory note, and your payment history, and our team will review it at no cost. If you decide to sell, closing typically takes 3–5 weeks when all documents are received and title is clear. Ready to sell mortgage note payments, or just want to know what a buyer would pay? We buy mortgage notes nationwide — Request a FREE Note Review anytime.